Security of property and individuals is a type of business activity that requires special rights. The basic rules are defined by the Law of Ukraine “On Security Activities”. The law regulates the ...
15Sep

In 2026, the basic principle remained unchanged: financial services can be provided by institutions and other persons who have the right to conduct the relevant activity as provided by law. The Law of Ukraine “On Financial Services and Financial Companies” allows combining the right to provide one or several financial services under a single license, if the law permits them for a specific type of institution.
The National Bank issues licenses, among others, for the activities of financial companies, insurers, credit unions, pawnshops, and for certain currency operations. The current types of permits issued by the NBU are published on the page about licensing of non-banking institutions.
For businesses, this means a simple thing: it’s not enough to register a legal entity and add the required classification code (KVED). The right to actually provide regulated financial services arises only after passing the relevant authorization procedure.
On Poshuk.info, there is a separate collection of companies offering support for obtaining licenses for financial services, and for new businesses, there is also a direction for registration of financial companies.
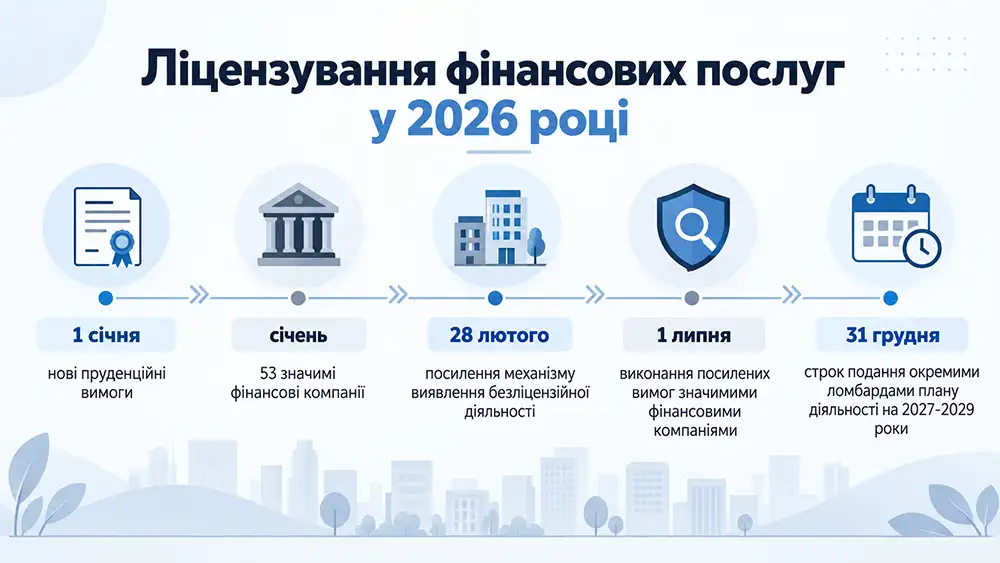
From February 28, 2026, changes approved by NBU Resolution No. 21 dated February 26, 2026, came into effect. They concern the definition of whether a particular service is a financial or limited payment service, as well as procedures for identifying unlicensed activities.
The regulator detailed the criteria it takes into account when making such decisions and the procedure for conducting in-depth analysis. The NBU also received a clarified mechanism for involving third parties in such analysis.
The risk for a company arises not only when the website explicitly mentions “credit” or “factoring.” The NBU may analyze the actual economic substance of the transaction.
When checking the business model, it is worth separately evaluating:
The actual model is key. The contract name does not change the legal nature of the transaction.
To understand the responsibility for conducting business without the necessary permission, the material on Poshuk.info about Art. 164 of the Code of Administrative Offenses is also relevant.
In January 2026, the NBU published the list of significant financial companies for the first time. It included 53 institutions. Enhanced requirements for corporate governance, activity planning, and information disclosure apply to them, which had to be fulfilled by July 1, 2026.
The status of a significant company affects not so much the fact of issuing a license, but more the subsequent compliance with activity conditions. The regulator reviews the management system much more deeply.
In particular, NBU Resolution No. 108 established the obligation of a significant financial company to prepare an activity plan for the second half of 2026 and for the 2027-2029 period. After increasing the authorized capital, such a company must notify the NBU and submit documents confirming the sources of funds within 15 working days.
NBU Resolution No. 69 dated June 24, 2026, became another noticeable update to the system. The document came into force on June 26 and changed the rules of authorization for both financial service providers and payment market participants.
Among the practically important changes:
A special rule concerns pawnshops that have the right to trade currency valuables in cash. They must develop an activity plan for 2027-2029 and submit it to the NBU by December 31, 2026.
In 2026, the transition from formal document verification to continuous risk-oriented supervision became especially noticeable. A company must comply with regulatory requirements not only on the day it receives the license.
The NBU controls the financial condition, ownership structure, business reputation of managers and significant shareholders, capital, internal control, risk management, and compliance with prudential standards. For some financial companies, updated prudential rules took effect precisely on January 1, 2026.
Therefore, preparation for licensing is advisable to be carried out sequentially:
The last point is of practical importance. During 2026, the rules have already changed several times, so a document package prepared according to an old template may not meet current requirements.
The specific package depends on the type of institution and financial services. There is no universal set for lending, factoring, financial leasing, guarantees, insurance, and payment services.
Before applying to the NBU, at minimum check:
An error at this stage can affect not only the document review period. If a company starts providing financial services before obtaining the necessary right or goes beyond the scope of the license, the issue moves from business registration to regulatory liability.
